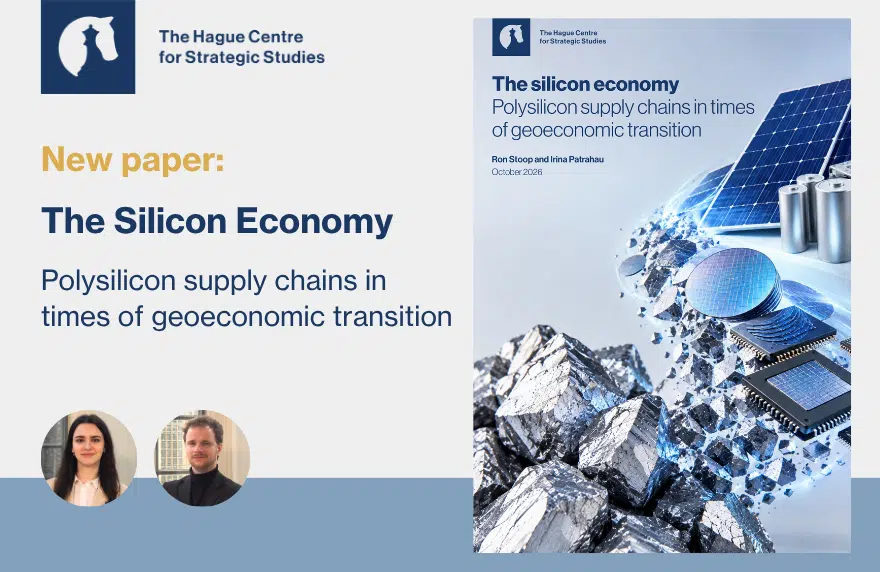
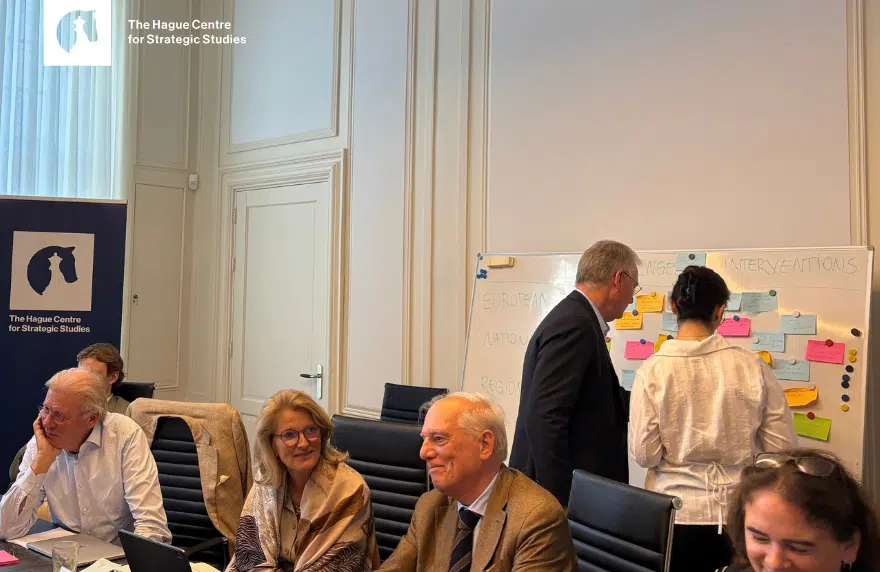
On 6 October 2026, HCSS hosted the closed-door roundtable “Polysilicon supply chains and geopolitical implications for the Netherlands and Europe”. In a new HCSS policy brief published this week, strategic analysts Ron Stoop and Irina Patrahau examine the geopolitical and industrial dynamics shaping Europe’s polysilicon supply chains and identify steps to strengthen their resilience.
Europe’s energy and digital transitions depend on secure access to critical materials, with polysilicon at the heart of solar, battery and semiconductor supply chains. In “The Silicon Economy”, Stoop and Patrahau identify vulnerabilities in Europe’s position and set out three priorities: coordinated supply chains, targeted EU financing and a tailored policy framework for polysilicon.
The policy brief provided the basis for the roundtable discussion among stakeholders from RESiLICON, the Ministry of Economic Affairs and Climate, the Ministry of Defence, ING, Invest International, the Province of Groningen, FME, and NOM.
Three main conclusions emerged from the discussion:
1. Europe’s declining position in polysilicon supply chains relative to other great powers is a strategic vulnerability.
Polysilicon is a foundational input for semiconductors and solar photovoltaics, yet Europe’s position in the supply chain is vulnerable. While the EU has some existing polysilicon production, this capacity alone cannot support policy ambitions to boost domestic solar-panel manufacturing under the Net-Zero Industry Act, nor can it guarantee that the EU maintains its role as a supplier of inputs for semiconductor production. Strengthening European polysilicon production, as the US, India, and China are doing, is therefore essential to increasing supply chain resilience and reducing geopolitical exposure.
2. Current financing and subsidy mechanisms in the Netherlands and the EU do not match the risk profile of critical raw materials projects.
Projects in critical raw material supply chains in the EU face a higher risk profile than more competitive projects, largely due to an uneven global playing field. Distributing risk among stakeholders and across the value chain is therefore key. Moreover, a significant share of relevant subsidies is inaccessible to early-stage projects, making it difficult to reach a final investment decision. Participants also noted that fragmented funding schemes and a lack of long-term investment horizons make it difficult to mobilise investment.
3. The immediate priority is to turn the discussion into coordinated action across the European solar and semiconductor value chains.
A new European polysilicon plant could serve as the foundation for a broader “Made in Europe” value chain, with downstream manufacturers depending on its products and by-products. Coordinating this effort requires a new approach to geopolitical thinking that makes clear choices, sets priorities, and can absorb the higher investment risk associated with strategic projects. The overarching conclusion was that the strategic case is clear; the challenge now is to determine who will take the first step.
Related Content